Monday, 9 June 2014

Forex Holy Grail Conclusions

 I wrote a detailed statistical follow-up showing how a trading strategy based upon securing a few very large winners can be an extremely profitable model to follow. Today I am going to write a concluding piece to this series, and provide a refined statistical analysis of comparative entry techniques. Last week’s piece did include a statistical error, but as often happens with errors if they are discovered in time, it led me to some interesting conclusions which I am going to share with you today.
First of all, a correction of the error in last week’s article has to be made. Statistics were shown that were described as the result of buying engulfing bars that make a 4 bar low and selling engulfing bars that make a 5 bar high, as reproduced below:
Chart 33114
In fact, the statistics shown above were produced by different criteria for entry, which were buying engulfing bars that make a 4 bar high and selling engulfing bars that make a 4 bar low: quite an essential difference!
This begs an obvious question: which entry strategy is superior? Buying the reversals at extremes, or as continuations within some kind of trend? This is what I will examine below, but to try to improve both sets of results I have added an additional filter, which is that the range of the trigger bar must not be larger than a defined maximum amount. It would have been more scientifically rigorous to use this as some measure of averaged range, but using a numerical value does about as well for our purpose. The maximum values used were as follows:
AUD/JPY: 40 pips
EUR/JPY: 60 pips
GBP/JPY: 50 pips
GOLD: $6
Additionally, bars under 10 pips or $1 were excluded from the samples.
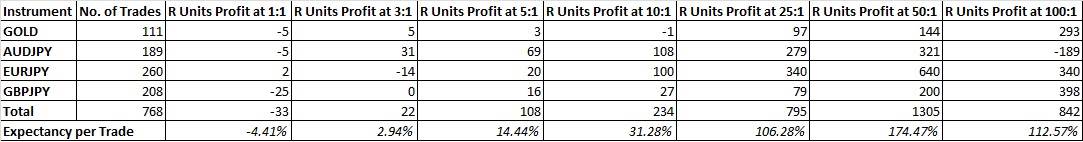
First of all, let’s see the results that were obtained by taking the extreme reversals, i.e. buying after a 4 bar low and selling after a 4 bar high as described above:
Chart 2 33114
Now let’s see how the “in-trend” variation performed, i.e. buying after a 4 bar high and selling after a 4 bar low:
Chart 3 33114
We can see that overall, at each different profit target, the expectancy per trade given by the “in-trend” variation is superior to the “extreme reversal” variation, and markedly so. The only real exception is Gold, and also GBPJPY to a slight extent.

Conclusion

Why should it be that the extreme reversal strategy is inferior? The simple answer is that although it gets you into the great trades early at excellent prices; it gets you into too many counter-trend trades. You get the winners, but you also get too many losers. By trading with the trend on the H4 chart as an alternative, your trades will be skewed in the direction of the prevailing trends, keeping you out of all those unnecessary losers.
What explains Gold’s contrary behaviour? Well, what has been very noticeable about Gold over the past few years is the violence and speed with which it reverses and follows through, as well as the fact that it has more or less both doubled and then halved in price in the space of just a few years, which is unlikely to repeated in the near future.
One important thing remains and that is to perform an “out of sample” test along similar lines over a similar time period previous to 2011. I have not completed that yet, but when I do, there will be an update to this series.

Forex Holy Grail Update

we published the latest instalment in our “Holy Grail” series, showing how a couple of fairly simple strategies performed over recent years.
An “out of sample” analysis of the same strategies has now been completed. This analysis looks at the hypothetical performances of the same strategies but over a different time period. It is always important to perform such an out of sample analysis when examining trading strategies. Our original statistics were based upon performance from the beginning of 2011 to the end of 2013. The out of sample analysis was conducted from the beginning of 2008 to the end of 2010, i.e. the immediately previous period of equal length.
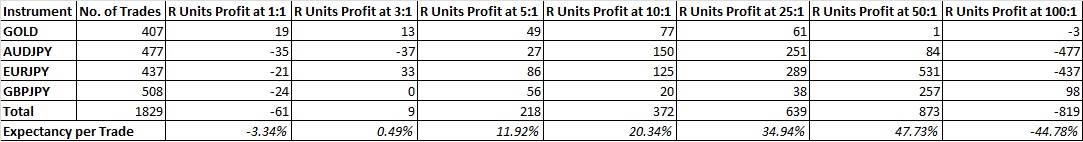
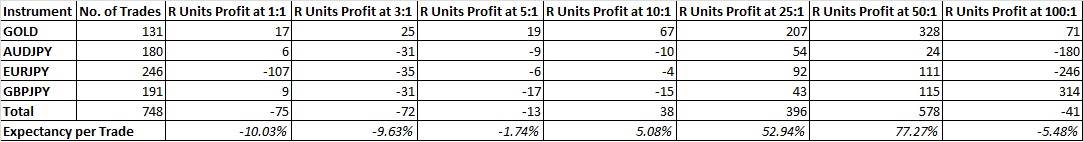
The results were fairly disappointing. The “reversal” strategy was somewhat profitable when traded with profit targets between 3:1 and 10:1. The “trend” strategy was not profitable on any profit target ratio. The numbers were as follows:

“Reversal” Strategy

Chart 41414

“Trend” Strategy

Chart 2 41414
In spite of the disappointment, it is worth noting that the “reversal” strategy, even without a directional bias, was proven to be potentially profitable during the out of sample period.
It is also worth noting that no technical criteria were used to select these currency pairs, at least for the out of sample test.
However, a strategy that is prepared to hold positions for long periods of time should be able to do much better than this, for the following reasons:

Overnight Charges

Brokers charge a small fee for every night you keep a trade open (in some cases, they may pay you a small rebate). This is due at least partly to the interest differential between the currencies. Many brokers also charge an additional fee which tends to mean that you almost always pay something overnight. Something in the region of 7 to 10 pips per week is common. This means that if you hold a trade for a 3,000 pip gain, but it takes a year to get there, you could pay something like 520 pips, giving up about one-sixth of your gains. The effect of these charges has not been included in the data presented within this series.

Pair Selection

One of the most commonly overlooked decisions a trader can make is which pairs to trade. Deciding which pairs should be traded at any time is probably the most important part of any long-term trading strategy. Often traders instinctively diversify, which has some advantages. But during those periods where almost the entire market is ranging, even diversified traders can suffer serious losses.

Directional Bias

A long-term trading strategy should be able to include a directional bias on each of the pairs it is trading. This means adapting to market conditions and deciding to only take either long or short trades, or perhaps both but differentially weighted. This should improve results dramatically as a strong trend would naturally result in the survival of multiple stacked positions that together create exponential profits from any strong trend, provided the bias is correct.

Moving Ahead

Next week, I will outline how a long-term trading strategy can be constructed in a way that works with rather than against the problems we looked at previously. The strategy will:
Begin with a methodology for selecting which pairs to trade and which directional bias to take, based upon the weekly time frame.
Continue with an entry strategy on lower time frames that is designed to ensure maximum “survivability” of positions, based upon the 4 hour time frame.
Conclude with a complete exit strategy.
See you next week!

Avoiding Psychological Traps That Ruin Your Trading

The mantra that 90% of the struggle to become a profitable trader is fought and decided within the trader’s own head has become a persistent cliché within Forex educational literature. Is it true, or is it just a convenient excuse to sell warmed-up, content-free New Age psychobabble at a huge mark-up? More importantly, does it mask a more sinister fact that the market is in fact random and cannot be beaten by any kind of analysis? The answers are mixed, and more complex than you might think.
There is no doubt that there is money to be made in the field of Forex education. A quick search of the net will produce a lot of material that is high on opinion and low on data. It is cheap and cost-effective to produce a little feel-good material for that section of the public that is ready to be talked out of the idea that it is gambling on short-term time frames without clear ideas of any realistic parameters. However, this in itself is not proof that the market is random and cannot be beaten by analysis.

The Illusion of Randomness

The idea that the market is random, when properly considered, is ridiculous. In fact, randomness in any context is wholly an illusion. It is just a word we ascribe to situations we feel that we cannot predict. In science, the apogee of randomness is the“Brownian Motion” experiment, where particles are observed moving randomly as they are buffeted by other unseen particles. However, if we knew the speed, mass and position of all the particles within the experiment, we would be able to predict the exact position and timing of every movement! It is exactly the same with financial markets. Price movements are caused by the value and timing of buy and sell transactions, and if we knew the intentions of every market participant we would be able to predict every tick of the market! So markets are not random, just effectively random to us on smaller time frames as we cannot possibly determine all the information required to accurately predict market movements.
The truth about technical analysis on smaller time frames is that it can provide a statistical edge, albeit a very small one. For example, certain technical formations, over large samples, might show a 53% probability that the price will reach 20 pips in one direction before the other. So the market can be beaten, even by technical analysis. It can be beaten even more easily by traders who realize that the same technical formations that show a 53% probability of 20 pips might also show a far more profitable 35% probability of 80 pips. All speculative markets can be beaten, in the long run, by strategies which cut losers short and allow winning trades to run in an unlimited fashion. This is because speculative financial markets consistently produce improbably excessive returns far more often than they would if they were efficient.

Why Do We Fear the Market?

Now we have established that it is possible to beat the market, why are so many traders, who understand and agree with my previous points, having problems with profitably exploiting the market?
This is where the New Age psychobabble comes in useful. In this context, it is not nonsense, but an accurate diagnosis. The short answer is: lack of belief, or faith. The trader is still frightened that they cannot beat the market, because the market has changed, or because the trade they are looking at taking right now looks terrible, etc. There is a long list of psychological issues that can be identified, but the lack of faith/belief is at the root of it all.

How to Believe You Can “Beat” the Market

How can this be challenged? It should be challenged on two levels: factual, and spiritual. The factual level is easier to prove. Simply construct a strategy that follows a trend on a longer time frame, uses a shorter time frame for entry, and seeks to hold positions until the longer time frame’s trend has changed while employing fairly tight stop losses on initial entries. It is best to try to trade instruments that are showing the most powerful trends also. Then test the strategy over a number of years. If the strategy is reasonably built and not over-curve fitted, you should like what you see. Note that there are losing periods, and remember these will test you far more as they play out in real time than they do as you click through a mountain of historical data over a period of a few hours of research.
The factual challenge was the easier part. What about the spiritual challenge? Deep down, most of us believe that “there is no such thing as a free lunch”. When this inner belief is combined with the fact that you have to risk money on the market in order to gain a return, we can feel foolish and guilty, like an arrogant child that is likely to harm themselves by not heeding the wise advice of their parents. This is what leads us to fail to take a trade, or close it out too early.
The first step in confronting this is to admit that the feeling exists within you. Understand why it exists. The final and most difficult step lies in persuading oneself that it is not true. Isn’t your life itself a “free lunch”? Did you have to work hard to be born? Were you born with some natural talents and positive attributes, and did you have to do any work to achieve them? Most of us are born with and continue to enjoy the unconditional love of our parents: did we have to earn that, or did it come free? Does the earth produce enough food, water and air to sustain us all, and before our ancestors took up farming, did they have to work very hard at hunting and gathering?
When you can truly accept that life itself is a free lunch, you will find that most of the battle to become a profitable trader has been won. Of course, you do need to do some work building and testing a strategy too, but that is the easier part.

How Retail Brokers use Overnight Swap Rates to Remove or Reduce their Clients' Trend-Following “Edge”

Recently, I came across an interesting trading strategy, intended for futures trading but theoretically applicable to retail Forex trading. The strategy’s author claims that even with completely objective and straightforward rules, a simple and complete “trend-following” strategy traded across a widely diversified group of liquid futures markets has produced an average annual return of approximately 20% per year over the past two decades, significantly outperforming global stock markets and equating to the kind of returns produced by professionally managed trend-following managed futures hedge funds.
As a Forex professional, I took a closer look at the strategy to see what kind of edge it might have historically provided to retail Forex traders. The results make interesting reading because they illustrate exactly why it can be so difficult for retail traders to exploit edges that exist within markets.
For the sake of full disclosure I reproduce the strategy rules in full:
Risk: the 100 day ATR (Average True Range) should equal 1 unit of risk.
Entry: long at the end of any day which closes above the highest close of the previous 50 days; short at the end of any day which closes below the lowest close of the previous 50 days.
Entry Filter: long entries only when the 50 day SMA (Simple Moving Average) is above the 100 day SMA; short entries only when the 50 day SMA is below the 100 day SMA.
Exit: A trailing stop should be used of 3 times the 100 day ATR from the highest price since the trade was opened (for longs), or the lowest price since the trade was opened (for shorts). The trailing stop must be recalculated constantly as a “chandelier stop” and it should be a soft stop: an exit is only made when a daily close is at or beyond the stop loss.
This strategy was tested against the most liquid and popular spot Forex currency pair, the EUR/USD, over a long and recent period of time (from September 2001 to the end of 2013), using publicly available spot EUR/USD data with the daily open and close at Midnight GMT.
The results show that the strategy provided a winning edge on EUR/USD during the test period. Over 366 trades, a total return of 33.85 units of risk was achieved, giving an average positive expectancy per trade of 9.25%. This means that the average trade produced a return equal to the amount risked plus an extra 9.25% of that amount. Considering the strategy is completely mechanical, and that it represents only one instrument within what is traditionally the worst-performing trend-following asset class (currency pairs), this is not such a bad result.
However, fees and commissions must be factored in, to determine the return that could actually have been enjoyed. Assuming that:
the trading was performed by a fund with EUR/USD futures contracts, and
a quarter of the trades had to be “rolled over” before the contract expired, incurring an additional commission, and
a “round trip” commission of $20 per trade had to be paid, and
an account of $10 million was traded with each unit of risk equaling a fixed 1% of the starting asset size, then
the total return would equal $3,385,000 minus 366 trades multiplied by $25 each, representing the commissions. This would mean a reduction of the return by only about 0.1%, giving a total return of 33.75%. It could be assumed that if the rolling over strategies were less than perfect, there would be some additional losses.
Imagine now a retail trader with an account of $10,000 who wants to trade this strategy using a retail Forex brokerage. Luckily for this trader, the brokerage allows access to some kind of approximation of a futures contract that can be traded with a very small lot size, as well as very small lot size spot Forex trading, so there is no problem with scalability.
The next step is to work out some likely costs of trading for the retail trader trying to implement this strategy over the same period on the EUR/USD. First of all we can look at the cost of using spot Forex:
Each trade incurs a spread of 2.5 pips, and
Each position that remains open at the New York close incurs an overnight swap charge that varies from position to position, but which averages out to, let’s say, three-quarters of a pip per night.
For the sake of simplicity we can perform a rough calculation based upon pips. The 33.85% return calculation was based upon a profit of 9,088 pips. The spread alone is 2.5 pips multiplied by the 336 trades, which are equal to 840 pips. Next, we must deduct the overnight swap charges. Our retail trader had a position open over 9,889 nights, which would account for 7,417 pips. So we must deduct a total of 8,257 pips from our total profit of 9,088 pips, which leaves a net profit of only 831 pips!
For the sake of this rough calculation, if we assume that the return is evenly spread over each pip, this represents a greatly reduced net profit to our retail trader of only 3.09%, as opposed to the 33.85% return achieved by the $10 million fund we looked at previously.
Our retail trader might have an alternative, which would be to buy synthetic mini futures contracts which do not incur overnight swap charges, but which have much wider spreads; something like 14 pips per trade for EUR/USD. Taking another look at the numbers and also assuming that one quarter of all trades must be rolled over, our retail trader would face a fee of 14 pips 458 times, equaling a deduction of 6,412 pips. This would represent a net profit of 2,676 pips. Assuming again that all return is spread equally over each pip, our retail trader ends with a net total return of 9.97%. So using synthetic mini-futures would have been much more profitable, but would still represent an annualized return over the test period of less than 1% profit per year! Furthermore, this return would be less than one third of the amount enjoyed by the large fund.

Breaking it down

Why are things so bleak for our retail trader? There are several reasons, and examining each reason carefully can help any aspiring retail trader understand how certain edges within the market can be effectively whittled away by the wrong choice of brokerage or execution methods.
Actual futures contracts are too large to be available to most retail traders, and position sizing cannot be achieved properly with amounts less than several million dollars in a diversified trend following strategy. Mini-futures are a potential solution, but if they are not very liquid then they are unlikely to present the same trend-following edge as ordinary futures. Exchange Traded Funds are another partial solution, but even so, the retail trader is going to have to pay some kind of spread for access to an appropriate market far in excess of the $20 round trip commission payable by a sizable client of a Futures Exchange.
This brings us to the topic of spreads. Frankly, there is no reason whatsoever why even a retail trader should be paying more than 1 pip for a round trip trade on an instrument as vanilla as the spot EUR/USD. Brokers charging more than this really have no valid excuse. It should be said that spreads in the retail sector have been going down in recent years. While this is good news, even if the retail trader in our example had been paying 1 pip instead of 2.5 pips, this would have raised profitability only by an additional 1.5%, and cannot truly be backdated all the way to 2001 in any case.
This brings us, finally, to the real culprit of the reduced return: the overnight swap rate, which is widely misunderstood, and so is worth a detailed examination.

Overnight Swap Charges

When you make a Forex trade, you are effectively borrowing one currency to exchange for another. You must therefore logically pay interest on the currency you are borrowing, while receiving in return interest on the currency you are holding in return. There is usually an interest rate differential between the two currencies, which means you should either be receiving or paying some extra fee each night representing the differential, and of course the exchange rate is a factor as currencies rarely trade at 1 to 1. The only time there would be nothing to pay or receive would be if the exchange rates were exactly equal at the rollover point, and there was no interest rate differential.
It would seem that sometimes you pay the difference and sometimes you receive it, so overall this swap cancels itself out. Unfortunately it is not as simple as that, for several reasons:
Currencies with higher interest rates tend to rise against currencies with lower interest rates, so you tend to find yourself in more long trades over time where you are borrowing the currency with the higher rate of interest, meaning you tend to be paying more often than receiving.
Retail Forex brokers charge or pay quite wildly different rates to their clients long or short of a particular pair. Many brokers are very opaque about this and do not even display the applicable rates on their websites, although the rates can be found within the brokerage feed on every MT4 platform. It is worth mentioning that, to be fair, there are legitimately different methods of calculating this charge. However if you look at the table compiled at myfxbook showing a range of overnight rates charged by some retail Forex brokers, you will get a sense of the wide variety in the market.
In addition to charging or paying the interest rate differential, some brokers also add an “administration” fee, which can mean that you will not receive anything even when the interest rate differential is positive in your favor! Ironically, these tend to be the same brokers that will bill you for account inactivity, and exactly what administration is involved when the trades are rarely even booked in the real market is highly questionable. The end result is to skew the fee even further against the client.
Most traders are highly leveraged, which means that they are borrowing the vast majority of the currency they are trading. Traders tend to forget that one of the negative consequences of leverage is to push up the overnight swap charges, as they must pay interest on all the borrowed money, and not just the margin that they are putting up on the particular trade. Of course, this is a legitimate element of the charge.
The practice of charging a fee for every night a client keeps a position open is not only open to abuse, but can be an effective way to dramatically reduce the odds that a trader might seek to move in their favor by an intelligent use of long-term trend trading, which usually pays off over time if executed properly. It might be said that some retail brokerages are using the widespread ignorance about these charges as a way to add to their balance sheets, and that regulatory agencies should be taking steps against this. On the other hand, it could also be said that a market maker cannot be expected to make a market in a way where they can be systematically put out of pocket by the long-term statistical behavior of the market. It might be that many of the differential rates between brokers are reflected by the currencies that their clients are long or short of at any particular time. It can be seen that one broker might be offering a better deal than another on one currency pair, but not on another, which seems strange.
A systematic study of this area would make a very interesting read. Meanwhile, a retail trader seeking to systematically hold positions overnight should make sure they fully investigate what is on offer when they are shopping around for brokers, and be aware that the speed of a price movement in their favor can have a big effect on the profitability of any trend or momentum strategies that they might be utilizing.
source;
How Retail Brokers use Overnight Swap Rates to Remove or Reduce their Clients' Trend-Following “Edge”

Recently, I came across an interesting trading strategy, intended for futures trading but theoretically applicable to retail Forex trading. The strategy’s author claims that even with completely objective and straightforward rules, a simple and complete “trend-following” strategy traded across a widely diversified group of liquid futures markets has produced an average annual return of approximately 20% per year over the past two decades, significantly outperforming global stock markets and equating to the kind of returns produced by professionally managed trend-following managed futures hedge funds.
As a Forex professional, I took a closer look at the strategy to see what kind of edge it might have historically provided to retail Forex traders. The results make interesting reading because they illustrate exactly why it can be so difficult for retail traders to exploit edges that exist within markets.
For the sake of full disclosure I reproduce the strategy rules in full:
Risk: the 100 day ATR (Average True Range) should equal 1 unit of risk.
Entry: long at the end of any day which closes above the highest close of the previous 50 days; short at the end of any day which closes below the lowest close of the previous 50 days.
Entry Filter: long entries only when the 50 day SMA (Simple Moving Average) is above the 100 day SMA; short entries only when the 50 day SMA is below the 100 day SMA.
Exit: A trailing stop should be used of 3 times the 100 day ATR from the highest price since the trade was opened (for longs), or the lowest price since the trade was opened (for shorts). The trailing stop must be recalculated constantly as a “chandelier stop” and it should be a soft stop: an exit is only made when a daily close is at or beyond the stop loss.
This strategy was tested against the most liquid and popular spot Forex currency pair, the EUR/USD, over a long and recent period of time (from September 2001 to the end of 2013), using publicly available spot EUR/USD data with the daily open and close at Midnight GMT.
The results show that the strategy provided a winning edge on EUR/USD during the test period. Over 366 trades, a total return of 33.85 units of risk was achieved, giving an average positive expectancy per trade of 9.25%. This means that the average trade produced a return equal to the amount risked plus an extra 9.25% of that amount. Considering the strategy is completely mechanical, and that it represents only one instrument within what is traditionally the worst-performing trend-following asset class (currency pairs), this is not such a bad result.
However, fees and commissions must be factored in, to determine the return that could actually have been enjoyed. Assuming that:
the trading was performed by a fund with EUR/USD futures contracts, and
a quarter of the trades had to be “rolled over” before the contract expired, incurring an additional commission, and
a “round trip” commission of $20 per trade had to be paid, and
an account of $10 million was traded with each unit of risk equaling a fixed 1% of the starting asset size, then
the total return would equal $3,385,000 minus 366 trades multiplied by $25 each, representing the commissions. This would mean a reduction of the return by only about 0.1%, giving a total return of 33.75%. It could be assumed that if the rolling over strategies were less than perfect, there would be some additional losses.
Imagine now a retail trader with an account of $10,000 who wants to trade this strategy using a retail Forex brokerage. Luckily for this trader, the brokerage allows access to some kind of approximation of a futures contract that can be traded with a very small lot size, as well as very small lot size spot Forex trading, so there is no problem with scalability.
The next step is to work out some likely costs of trading for the retail trader trying to implement this strategy over the same period on the EUR/USD. First of all we can look at the cost of using spot Forex:
Each trade incurs a spread of 2.5 pips, and
Each position that remains open at the New York close incurs an overnight swap charge that varies from position to position, but which averages out to, let’s say, three-quarters of a pip per night.
For the sake of simplicity we can perform a rough calculation based upon pips. The 33.85% return calculation was based upon a profit of 9,088 pips. The spread alone is 2.5 pips multiplied by the 336 trades, which are equal to 840 pips. Next, we must deduct the overnight swap charges. Our retail trader had a position open over 9,889 nights, which would account for 7,417 pips. So we must deduct a total of 8,257 pips from our total profit of 9,088 pips, which leaves a net profit of only 831 pips!
For the sake of this rough calculation, if we assume that the return is evenly spread over each pip, this represents a greatly reduced net profit to our retail trader of only 3.09%, as opposed to the 33.85% return achieved by the $10 million fund we looked at previously.
Our retail trader might have an alternative, which would be to buy synthetic mini futures contracts which do not incur overnight swap charges, but which have much wider spreads; something like 14 pips per trade for EUR/USD. Taking another look at the numbers and also assuming that one quarter of all trades must be rolled over, our retail trader would face a fee of 14 pips 458 times, equaling a deduction of 6,412 pips. This would represent a net profit of 2,676 pips. Assuming again that all return is spread equally over each pip, our retail trader ends with a net total return of 9.97%. So using synthetic mini-futures would have been much more profitable, but would still represent an annualized return over the test period of less than 1% profit per year! Furthermore, this return would be less than one third of the amount enjoyed by the large fund.

Breaking it down

Why are things so bleak for our retail trader? There are several reasons, and examining each reason carefully can help any aspiring retail trader understand how certain edges within the market can be effectively whittled away by the wrong choice of brokerage or execution methods.
Actual futures contracts are too large to be available to most retail traders, and position sizing cannot be achieved properly with amounts less than several million dollars in a diversified trend following strategy. Mini-futures are a potential solution, but if they are not very liquid then they are unlikely to present the same trend-following edge as ordinary futures. Exchange Traded Funds are another partial solution, but even so, the retail trader is going to have to pay some kind of spread for access to an appropriate market far in excess of the $20 round trip commission payable by a sizable client of a Futures Exchange.
This brings us to the topic of spreads. Frankly, there is no reason whatsoever why even a retail trader should be paying more than 1 pip for a round trip trade on an instrument as vanilla as the spot EUR/USD. Brokers charging more than this really have no valid excuse. It should be said that spreads in the retail sector have been going down in recent years. While this is good news, even if the retail trader in our example had been paying 1 pip instead of 2.5 pips, this would have raised profitability only by an additional 1.5%, and cannot truly be backdated all the way to 2001 in any case.
This brings us, finally, to the real culprit of the reduced return: the overnight swap rate, which is widely misunderstood, and so is worth a detailed examination.

Overnight Swap Charges

When you make a Forex trade, you are effectively borrowing one currency to exchange for another. You must therefore logically pay interest on the currency you are borrowing, while receiving in return interest on the currency you are holding in return. There is usually an interest rate differential between the two currencies, which means you should either be receiving or paying some extra fee each night representing the differential, and of course the exchange rate is a factor as currencies rarely trade at 1 to 1. The only time there would be nothing to pay or receive would be if the exchange rates were exactly equal at the rollover point, and there was no interest rate differential.
It would seem that sometimes you pay the difference and sometimes you receive it, so overall this swap cancels itself out. Unfortunately it is not as simple as that, for several reasons:
Currencies with higher interest rates tend to rise against currencies with lower interest rates, so you tend to find yourself in more long trades over time where you are borrowing the currency with the higher rate of interest, meaning you tend to be paying more often than receiving.
Retail Forex brokers charge or pay quite wildly different rates to their clients long or short of a particular pair. Many brokers are very opaque about this and do not even display the applicable rates on their websites, although the rates can be found within the brokerage feed on every MT4 platform. It is worth mentioning that, to be fair, there are legitimately different methods of calculating this charge. However if you look at the table compiled at myfxbook showing a range of overnight rates charged by some retail Forex brokers, you will get a sense of the wide variety in the market.
In addition to charging or paying the interest rate differential, some brokers also add an “administration” fee, which can mean that you will not receive anything even when the interest rate differential is positive in your favor! Ironically, these tend to be the same brokers that will bill you for account inactivity, and exactly what administration is involved when the trades are rarely even booked in the real market is highly questionable. The end result is to skew the fee even further against the client.
Most traders are highly leveraged, which means that they are borrowing the vast majority of the currency they are trading. Traders tend to forget that one of the negative consequences of leverage is to push up the overnight swap charges, as they must pay interest on all the borrowed money, and not just the margin that they are putting up on the particular trade. Of course, this is a legitimate element of the charge.
The practice of charging a fee for every night a client keeps a position open is not only open to abuse, but can be an effective way to dramatically reduce the odds that a trader might seek to move in their favor by an intelligent use of long-term trend trading, which usually pays off over time if executed properly. It might be said that some retail brokerages are using the widespread ignorance about these charges as a way to add to their balance sheets, and that regulatory agencies should be taking steps against this. On the other hand, it could also be said that a market maker cannot be expected to make a market in a way where they can be systematically put out of pocket by the long-term statistical behavior of the market. It might be that many of the differential rates between brokers are reflected by the currencies that their clients are long or short of at any particular time. It can be seen that one broker might be offering a better deal than another on one currency pair, but not on another, which seems strange.
A systematic study of this area would make a very interesting read. Meanwhile, a retail trader seeking to systematically hold positions overnight should make sure they fully investigate what is on offer when they are shopping around for brokers, and be aware that the speed of a price movement in their favor can have a big effect on the profitability of any trend or momentum strategies that they might be utilizing.